Could Your Credit Card Limit Be Affecting Your Home Loan?
When you're preparing to buy a home, you might assume that the main things lenders care about are your income, savings and current debts.
But there’s another factor that can sometimes catch buyers off guard: your credit card limits.
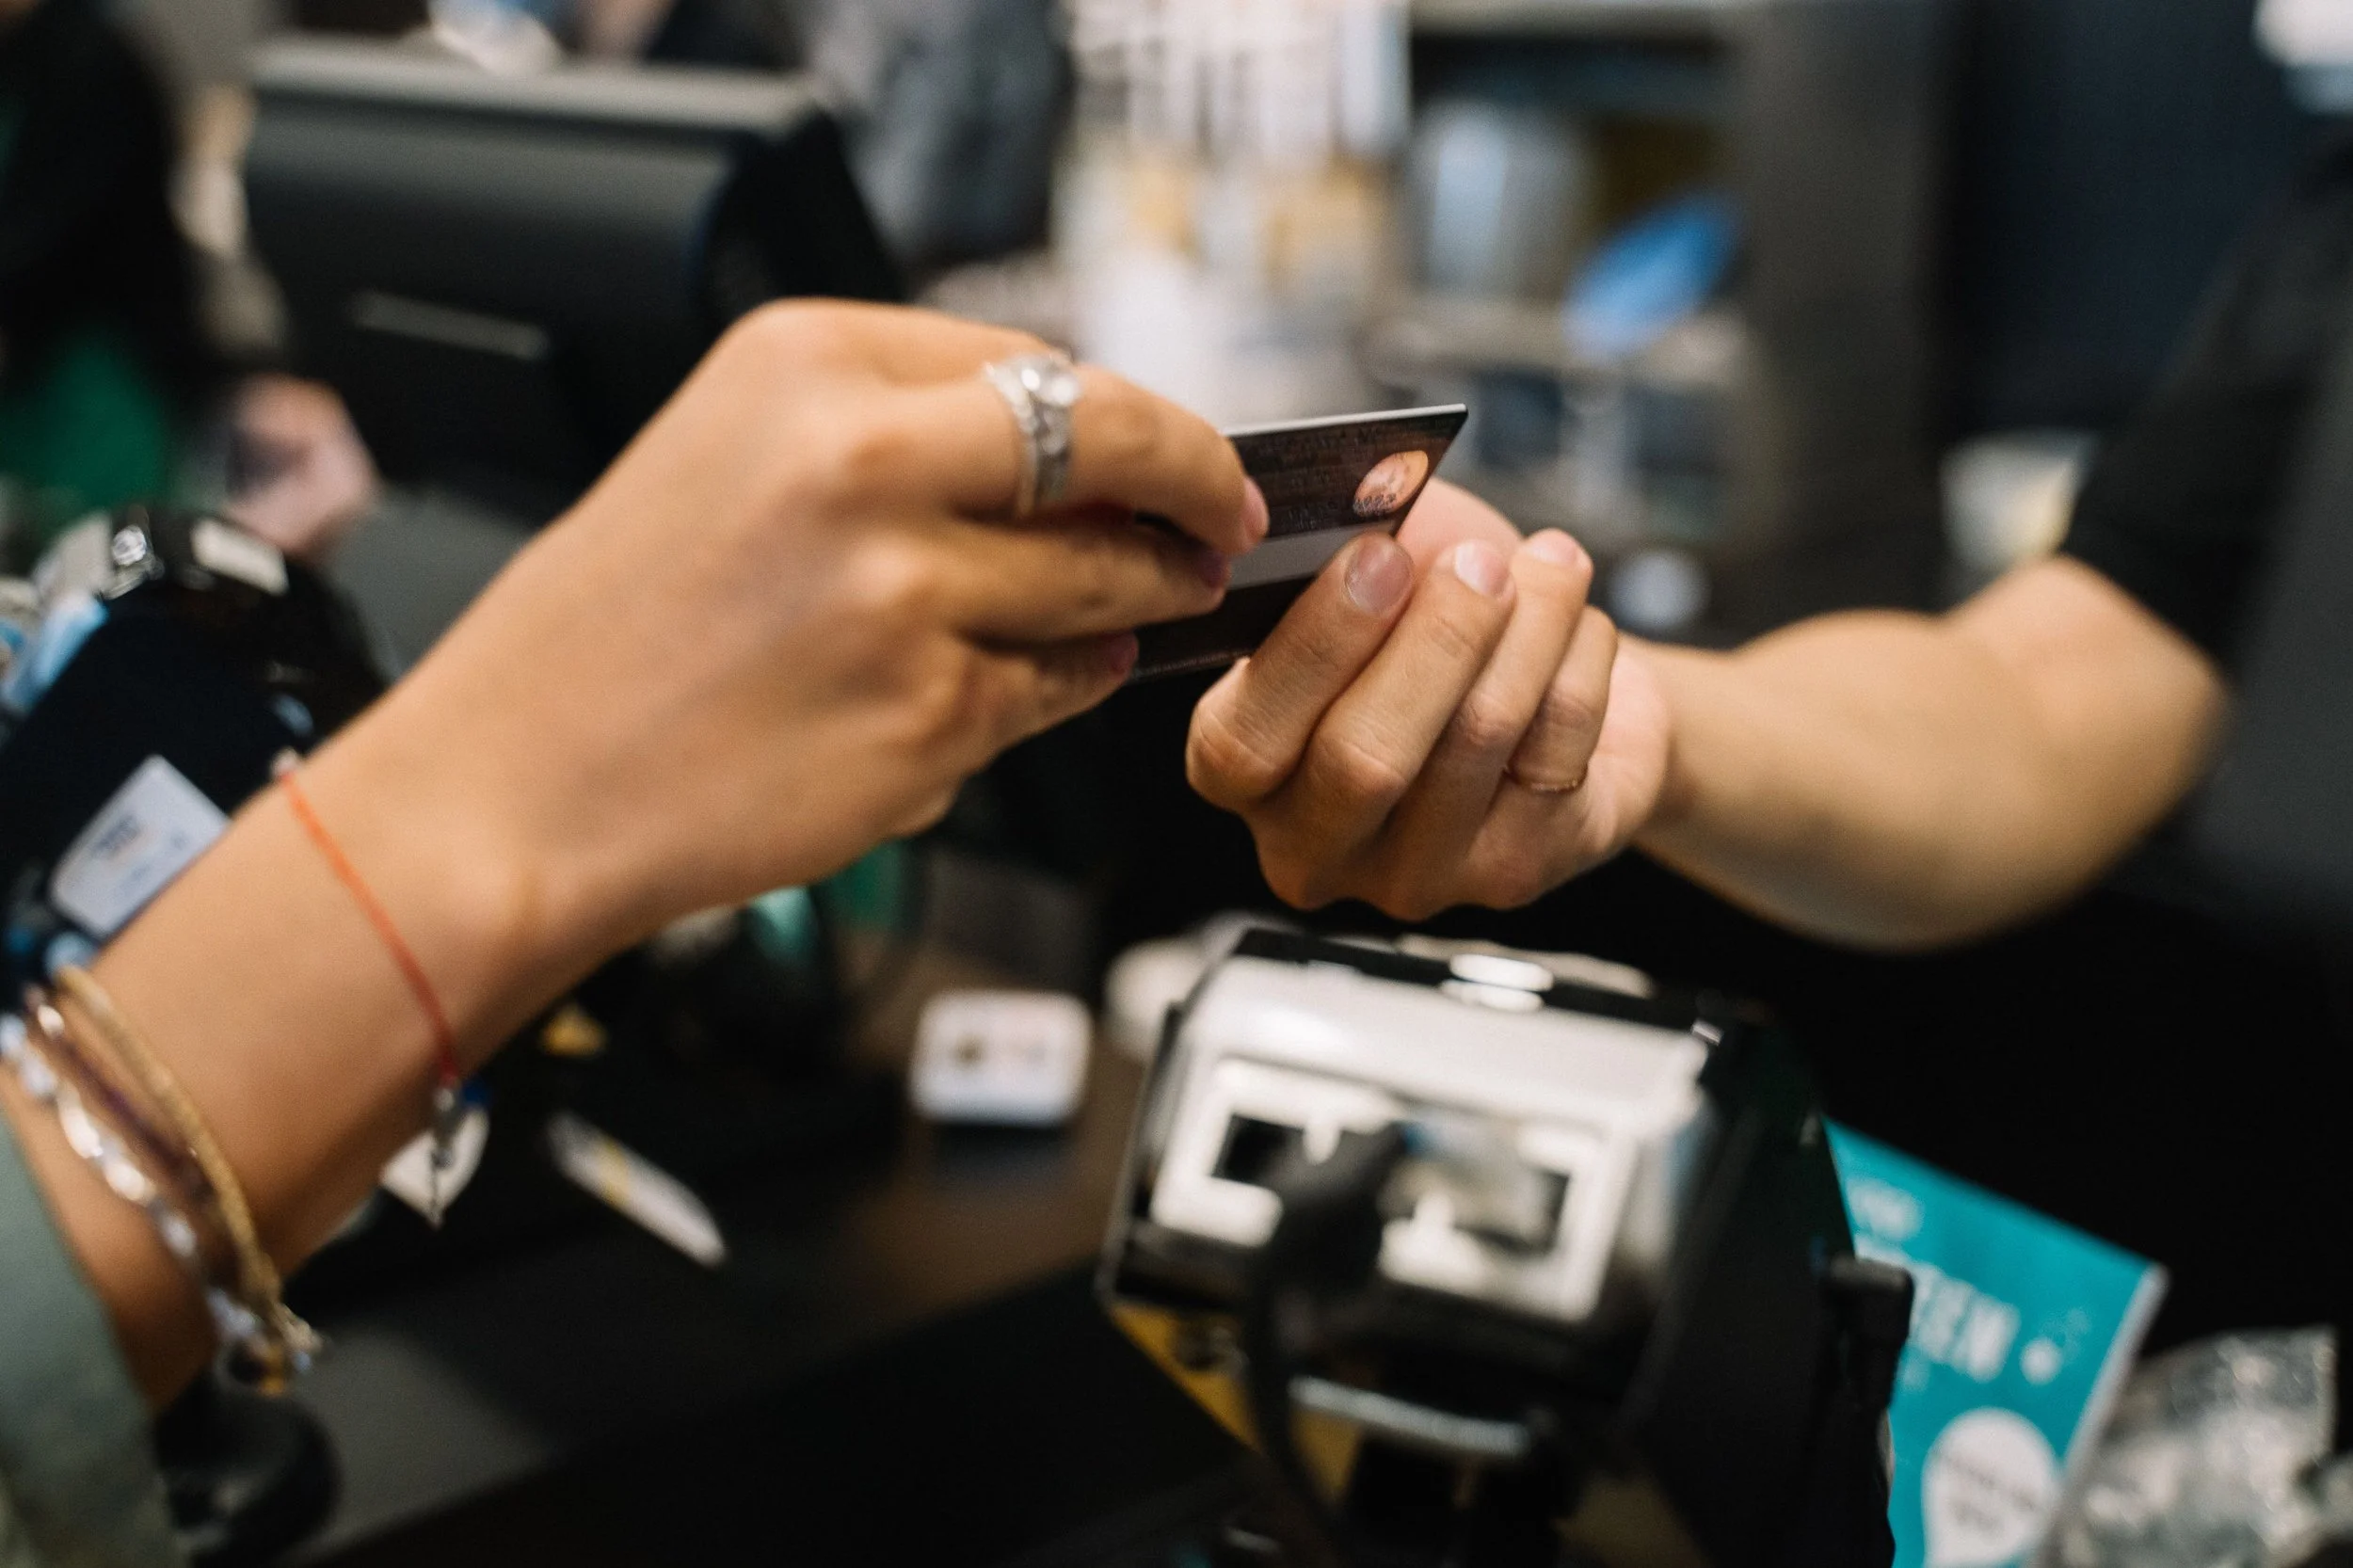
Even if you have a $0 balance and always pay your card off in full, your available credit can still be considered when a lender assesses your borrowing capacity.
Your credit limit matters, not just your balance
Let's say you have a credit card with a $15,000 limit, but you currently owe nothing on it.
You might think, “I don't have any credit card debt, so it shouldn't affect my home loan.”
However, lenders may consider the full credit limit when assessing your application because that amount of credit is available to you if you were to use it.
This means having a high credit limit could potentially reduce the amount a lender is prepared to lend, even if you're not actually using the card.
Multiple credit cards can add up
The impact can become more noticeable if you have several credit cards or other credit facilities.
For example:
Credit card 1: $10,000 limit
Credit card 2: $8,000 limit
Credit card 3: $5,000 limit
That's $23,000 of available credit, despite having no outstanding balance.
From a lender's perspective, these existing credit commitments can form part of their assessment of your ability to manage additional debt.
What can you do before applying for a home loan?
If you're thinking about buying a property, it's worth reviewing your existing debts and credit facilities before applying for finance.
Depending on your circumstances, this could include:
Reducing unnecessary credit card limits
Closing credit cards you no longer use
Paying down existing debts
Reviewing Buy Now, Pay Later accounts and other credit facilities
However, it's important not to make changes simply because you've heard they could improve your borrowing capacity. The right approach will depend on your overall financial position and circumstances.
Don't wait until you've found a property
One of the biggest mistakes buyers can make is leaving their finances until after they've started house hunting.
Before you start saving properties and booking inspections, it can be worthwhile understanding your borrowing capacity and identifying anything that could potentially affect your application.
If you're thinking about buying a home, speak to WestGen Finance about your options.